Personal Lines Inland Flood Coverage Endorsement
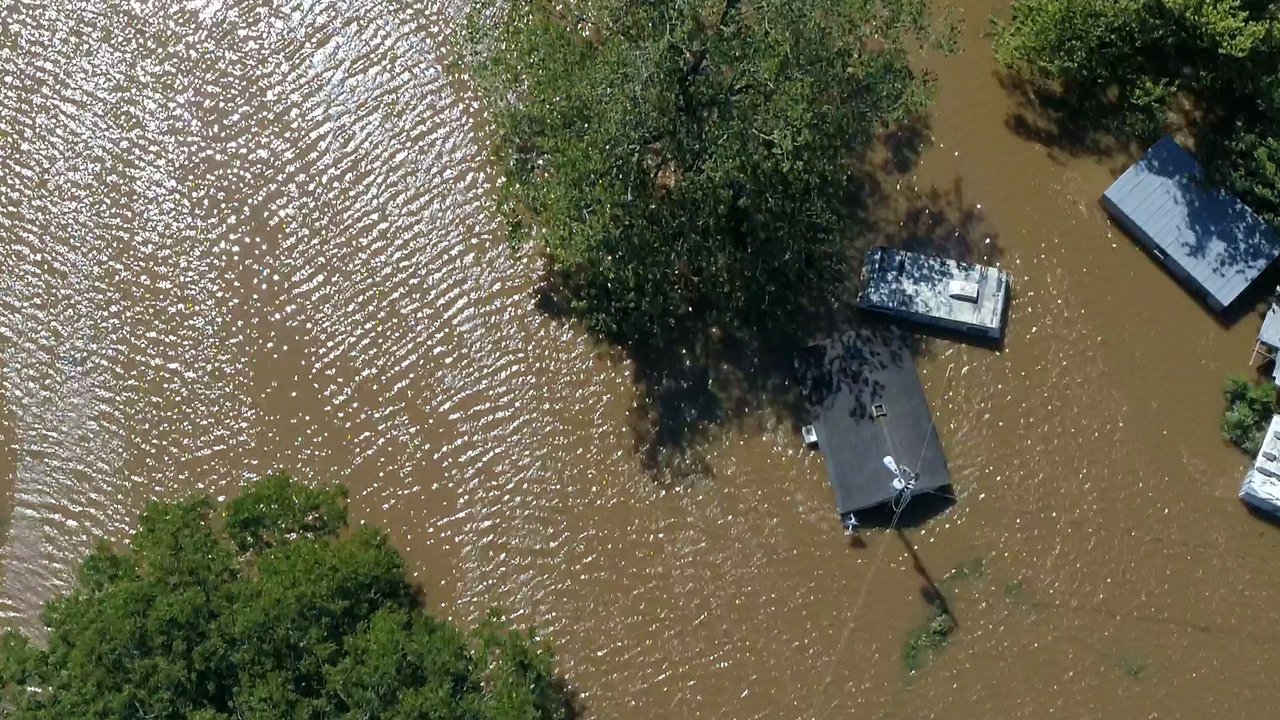
Flooding is no longer just a coastal concern. From devastating inundation in Kentucky to severe convective storms across the Plains and Midwest, flood-related losses continue to impact communities nationwide.
Yet despite the growing threat, a significant protection gap remains. According to FEMA, fewer than 4% of US homes carry flood insurance. At the same time, Moody’s estimates that insured flood losses totaled approximately $319bn between 2000 and 2024, while uninsured losses exceeded $1.58tn over the same period.
<4%
Homes have flood coverage in place, according to FEMA.
$319bn
Insured flood losses from 2000 to 2024 according to Moody's.
$1.58tn
Uninsured losses from 2000 to 2024 according to Moody's.
As flood risk expands beyond traditionally mapped high-hazard areas, insurers and agents are looking for ways to make coverage more accessible and affordable. One solution is flood endorsements attached to homeowners policies.
“Forty percent of National Flood Insurance Program (NFIP) claims come from outside Special Flood Hazard Areas (SFHA),” said Seth Piechowski, Senior Market Development Manager at Munich Re US. “That highlights the need for coverage options that address inland and lower-risk flood exposures, where many property owners may not perceive flood as a significant threat.”
Addressing affordability without sacrificing protection
For many homeowners outside high-risk zones, purchasing a standalone flood policy can be difficult to justify. Premiums may be substantial relative to the perceived risk, leading many property owners to forgo coverage entirely.
Flood endorsements provide an alternative approach by offering supplemental flood protection through an existing homeowners policy, often at a significantly lower cost than a standalone policy.
For many flood losses, particularly in inland areas, damages can reach tens of thousands of dollars. An endorsement can provide meaningful protection against those more common loss scenarios while helping homeowners manage costs.
By lowering barriers to entry, endorsements can help carriers extend flood protection to policyholders who otherwise may choose to remain uninsured.
Simplifying the insurance experience
Beyond affordability, endorsements may also reduce operational complexity for both policyholders and agents. Because flood coverage is added to an existing policy, agents can avoid managing separate applications, policy administration processes, and renewal cycles associated with standalone flood products.
“The process is streamlined for both the agent and the customer,” Piechowski said. “Coverage can be added directly to an existing policy rather than requiring an entirely separate insurance transaction.”
Claims handling may also become simpler when a flood event occurs. Rather than coordinating among multiple carriers and adjusters, policyholders can often work with a single insurer when multiple causes of loss are involved.
“When flood damage occurs alongside other covered perils, working with a single carrier can help reduce complexity during the claims process,” Piechowski noted. “It creates a more seamless experience for the insured at a time when clarity is especially important.”
Expanding resilience through broader coverage adoption
As weather-related catastrophes become more frequent and geographically widespread, increasing insurance participation remains a key challenge for the industry.
For insurers, flood endorsements represent an opportunity to broaden flood coverage penetration among homeowners who live outside designated flood zones but still face meaningful exposure. For policyholders, they offer an accessible means of transferring flood risk that might otherwise be retained.
“Many homeowners assume they’re not at risk because they aren’t located in a high-hazard flood zone,” Piechowski said. “However, flood losses occur in communities across the country. Providing affordable coverage options is an important step toward narrowing the protection gap.”
By partnering with Munich Re US, carriers can offer the Personal Lines Inland Flood Coverage Endorsement, a customizable white-label flood solution designed for property owners outside Special Flood Hazard Areas, helping improve resilience while addressing one of the industry’s most persistent coverage challenges.
Personal Lines Inland Flood Coverage Endorsement
Experts