Munich Re US’ Applied Analytics team is transforming data into actionable insights

The US property insurance sector is going through a turbulent time, with rising catastrophic losses and market volatility leaving clients looking for new ideas to help manage these risks. In 2025, global insured natural catastrophe (CAT) losses exceeded $107 billion and, in Q1 of 2026, the US accounted for roughly 75% of global natural disaster insured losses.
$107bn+
Global insured natural catastrophe (CAT) losses in 2025.
~75%
Of global natural disaster insured losses in Q1 of 2026 were in the US.
Volatility and portfolio concentration
In a recent interview with Insurance Business (“IB”), Jason Dunn, SVP, Digital Product Manager at Munich Re US, explained that he’s seen two major pain points for clients in this space recently and revealed how Munich Re US’ team is perfectly poised to help.
“The first is around unprecedented volatility,” he told IB. “Clients are struggling to manage the unpredictability of recent CAT losses that are escaping traditional CAT model approaches. The second pain point is identifying portfolio concentration and the hidden risk accumulations in what have been historically low- to moderate-risk areas. This is primarily due to either shifting weather patterns or more extreme weather events.”
Client pain points relating to nat cat portfolio management
Managing unprecedented volatility
Identifying portfolio concentration and hidden risk accumulations
At Munich Re US, the Applied Analytics team helps clients to better understand these two things in parallel.
“With the unprecedented volatility, we are able to leverage our position as a leading property reinsurer in the US by helping clients improve their benchmarking and market share analysis, and pinpointing critical exposure management insights,” added Dunn. “While most carriers today can understand their relative market share on a premium basis, we have access to every single location in the US for personal lines or commercial lines, and we can do a hyper-localized market share analysis for our clients. Then, we combine this with our other available data sets, including our high-definition hazard maps. When you combine these two things, the hyper-localized market share with high-definition risk insights, we’re able to help carriers steer their portfolio around changing accumulation or exposure.”
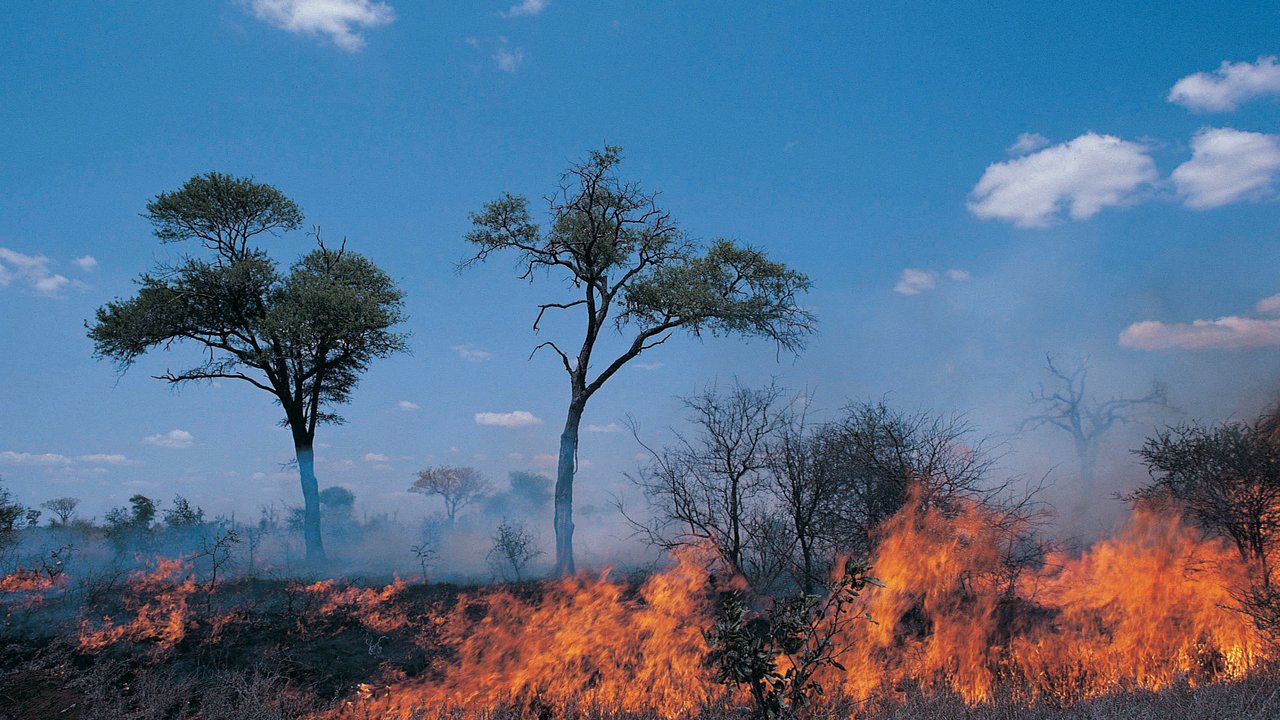
Wildfires still worrying Western US
Regarding specific CAT exposures, Dunn revealed that wildfires are still a main concern for clients. The infamous California wildfires reportedly generated roughly $40 billion in insured losses in Q1 2025 alone, and carriers are understandably worried that 2026 may follow the same pattern.
“Both wildfires and the smoke they produce continue to be a concern for many people,” Dunn told IB. “There are a few different elements to this. The first is the impact of these wildfires transitioning into urban conflagrations, spreading rapidly through densely populated areas, destroying entire neighborhoods or cities. With this transition, we see a huge increase in the number of people exposed to wildfire smoke. Wildfires are occurring right next to major population centers. This stresses the system by putting a strain on claims adjusters, industrial hygienists, and remediation crews needed to address every single home in these densely populated areas.
Carriers need to think about how they can better triage their resources to make sure they’re prioritizing their claims people and their cleanup efforts to the areas that are most impacted. At Munich Re US, we help clients by providing a real-time view on wildfire smoke.
“There are many toxic materials like asbestos, heavy metals, chemicals, and lead — things that you don’t really want to breathe in,” Dunn told IB. “And you don’t want them inside your house.”
“We do this by looking at air quality data and smoke density over time so clients can see where the smoke was most dense or most damaging on any given day. From there, they can also use this information historically as they manage their claims decisions going forward.”
It’s this access to data and benchmarking analysis that sets Munich Re US apart. As Dunn told IB, utilizing this benchmarking to develop insights means they can provide strong support to their clients proactively. Dunn recalled an instance where he saw this support play out in real time, when a regional client was facing intense pressure to cut back their property writing in California due to several years of bad wildfire losses.
Dunn said, “However, the client, in this case, lacked the granular data to know where they could grow their business or where they were overexposed from a wildfire perspective. Here, Munich Re US provided our wildfire benchmarking and risk scoring tool, which brought in their data and combined it with market data to help them understand where they were overexposed.
It also gave them hazard scores that helped the client understand which locations were more exposed to wildfire risk with up-to-date and high-definition views. As a result of those two things, the client was able to restructure their underwriting appetite. They optimized their portfolio to trim away from those higher-risk exposures and navigate their portfolio into more profitable areas.”
Leveraging AI – scale and speed
All of this innovation rests on the shoulders of one core component: market-leading technology. Or, more specifically, AI.
“Our team is leveraging AI,” added Dunn. “At Munich Re US, where we see it most impactful is with pattern recognition at scale and the speed at which we can gain insights. We use AI-based tools to evaluate large, unstructured data sets, typically geospatial and climate data sets.”
And the market seems to agree with Dunn here. Data from Earnix’s 2026 Insurance Trends Report found that 81% of insurance executives report that AI is embedded across most or some of their workflows.
“We feel like we have a valuable role here”
Looking ahead to what the next three to five years may bring, Dunn told IB that this intersection of AI, geospatial data, and property insurance is set to grow and become even stronger.
“Underwriters are likely looking to access multiple data points to improve their understanding or be challenged by different data sets in a changing risk environment. It’s about gathering informed views on how climate change will impact risk and then translating these long-term climate projections into localized and immediate views.
As a leading property reinsurer in the US, we have a valuable role here. We are dedicated to working with our clients to better understand the ever-changing risk environments and these long-term trends.
Munich Re US’ Applied Analytics team is transforming data into actionable insights
This article was produced by Insurance Business America, in collaboration with Munich Re US.
Our expert